


Prediction: This Forgotten Tech Stock Could Make a Comeback by 2028
Prediction: This Forgotten Tech Stock Could Make a Comeback by 2028
Vandita JadejaTue, October 20, 2026 at 4:00 PM UTC
0
VideoFlow / Shutterstock.com (VideoFlow / Shutterstock.com)Quick Read -
Cisco (CSCO) trades at 20x forward earnings with a $125.51 price target, implying 17% upside and a base case of $138 by 2028.
Arista (ANET) trades at 39x forward earnings while HPE carries a 4.8% operating margin, making Cisco's valuation the sweet spot between both peers.
Cisco expects AI infrastructure revenue to nearly double to $7.5 billion in FY2027, with CEO Chuck Robbins calling it the start of a "super cycle."
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Cisco Systems (NASDAQ:CSCO) spent years as the networking giant that growth investors passed over. AI is pulling it back into the public eye.
The 24/7 Wall St. price target for Cisco is $125.51, which implies 16.87% upside from $107.39. The model is highly confident in its buy rating for the stock.
Metric
Value
Current Price
$107.39
Price Target from 24/7 Wall St.
$125.51
Upside/Downside
16.87%
Recommendation
Confidence Level
90%
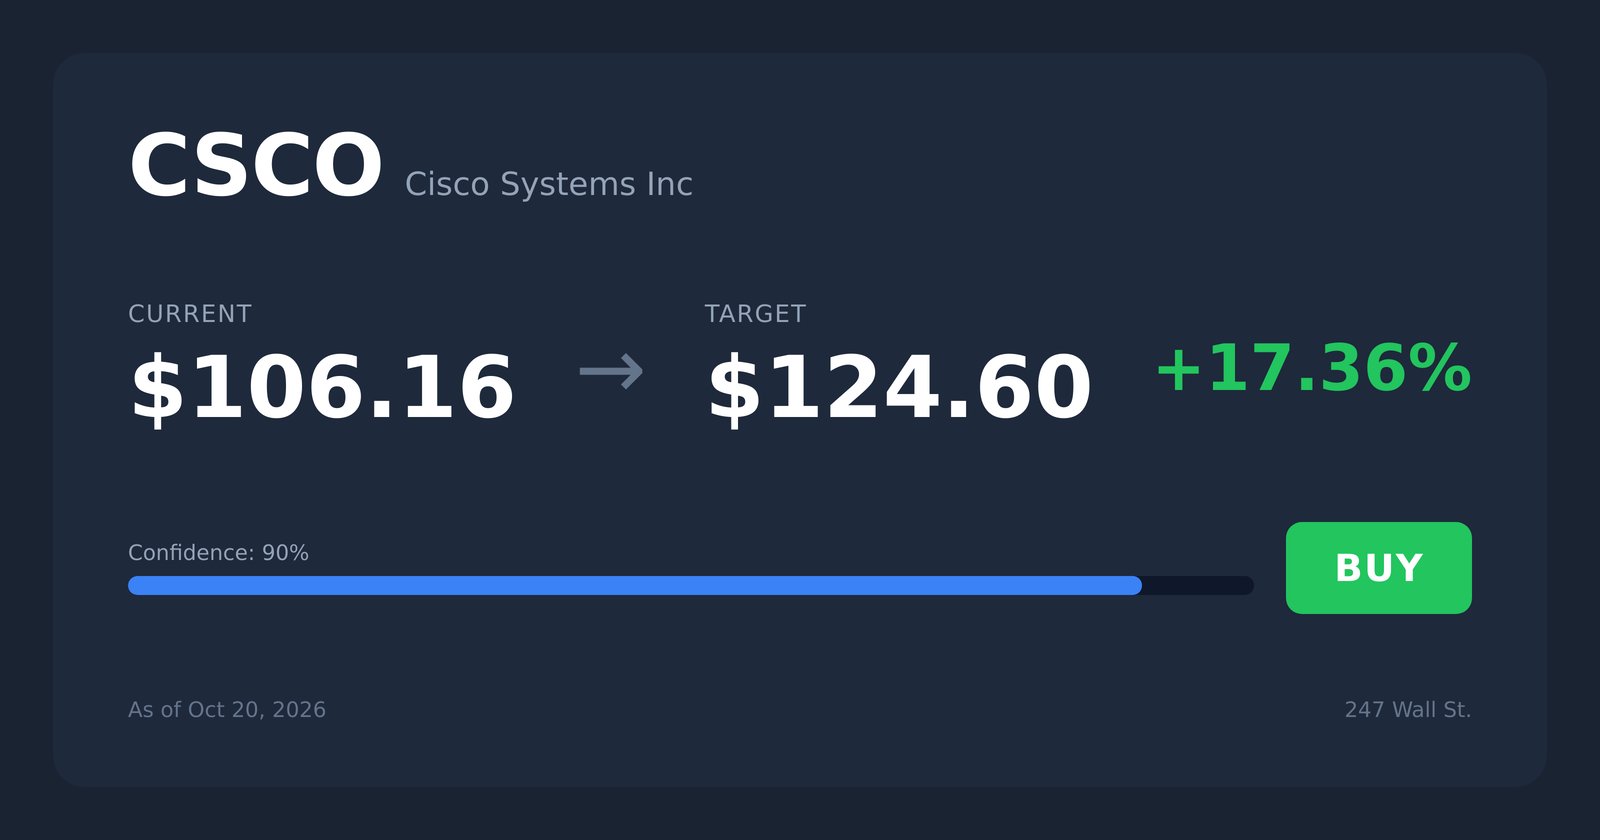
CSCO Price Target — 24/7 Wall St.
The comeback case rests on AI infrastructure revenue. Cisco expects AI infrastructure revenue to reach $7.5 billion in FY2027, up from about $4 billion in FY2026. If that ramp holds, our model's base case reaches $138.03 by October 2028.
Cisco is one of the names gaining as hyperscalers pour money into the picks-and-shovels side of AI (we featured seven of these non-chipmaker suppliers in a free report you can grab here).
A Sharp Weekly Pullback Follows a Strong 2026 Rally
Shares fell 9.29% over the past week and are about flat over one month (+0.05%). They are still up 41.96% year to date. The stock sits about 17% below its 52-week high of $129.38 and about 57% above its low of $68.58.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
Fiscal Q4 revenue rose 17.58% to $17.25 billion, ahead of the $16.83 billion estimate. Non-GAAP EPS of $1.22 exceeded expectations of $1.17. Even so, the stock slipped after the report on margin concerns, and Piper Sandler cut its price target in September.
Why Bulls See $136 and Beyond
Management guides FY2027 revenue to $72.2 billion to $73.4 billion and non-GAAP EPS to $5.05 to $5.11. Q4 product orders rose 35%, and Cisco won three new hyperscaler design wins. Hyperscaler AI grew to about 6% of total revenue, up from under 2%.
Advertisement
Chuck Robbins said, "We believe we're only at the beginning of this super cycle." The consensus target is $136.16, supported by 19 bullish ratings and no sells. Our bull case is $136.52.
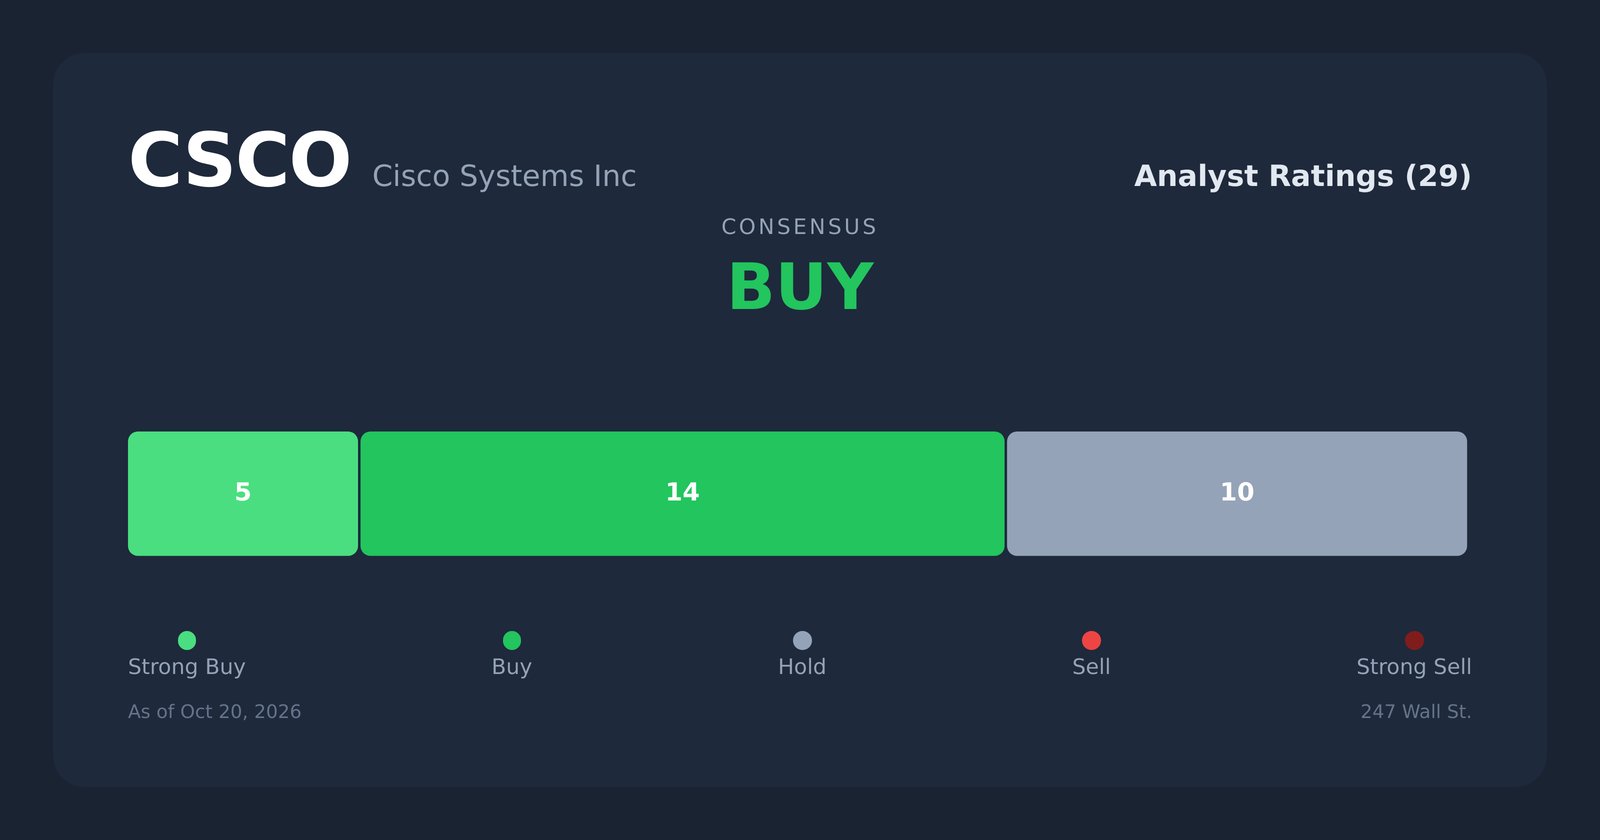
CSCO Analyst Ratings — 24/7 Wall St.Margin Pressure and Hyperscaler Dependence Could Stall the Comeback
Non-GAAP gross margin slipped to 66.3% from 68.4% as hardware became a bigger share of sales. Price increases added about five points to Q4 growth, and FY2026 operating cash flow fell 0.11%. Restructuring charges continue through FY2027.
CFO Mark Patterson pushed back on the margin worry: lower-margin hardware "actually turns out to be highly profitable because we don't have to add incremental expenses." Our bear case is $106.37.
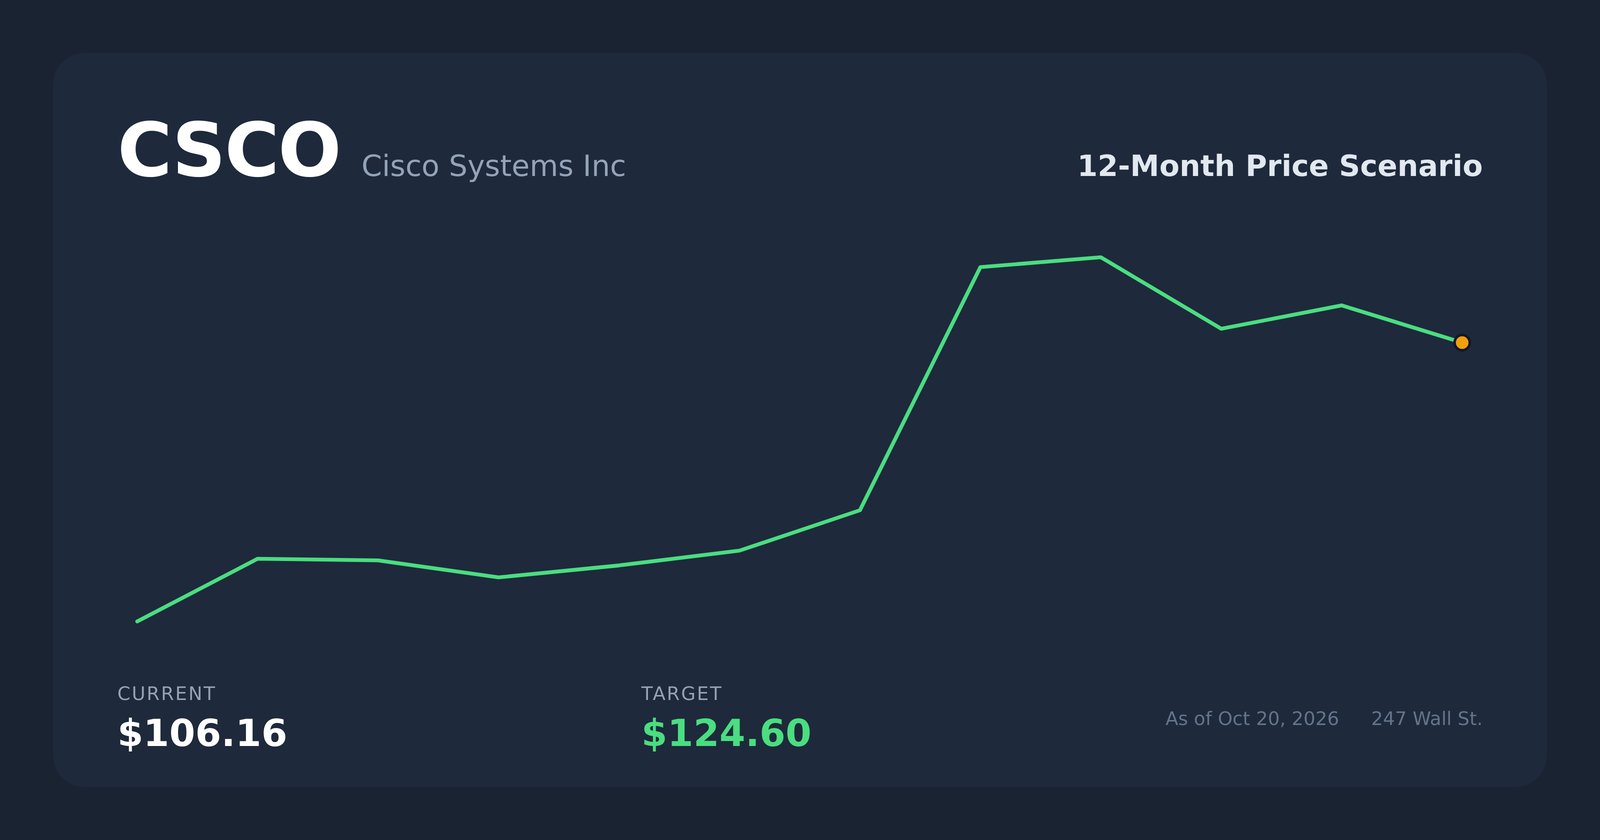
CSCO Price Scenario — 24/7 Wall St.Cisco Trades at Half Arista's Multiple
Arista Networks (NYSE:ANET) competes directly with Cisco for AI data center switching. Revenue grew 37.7% last quarter, which helps explain why the stock trades at a forward P/E of 39, about twice Cisco's.
Hewlett Packard Enterprise (NYSE:HPE) now has Juniper Networks and posted 74.9% networking growth. However, its 4.8% operating margin is far below Cisco's. With HPE at the low end and Arista at the high end, Cisco's valuation looks reasonable, and our target leaves room for upside.
Company
Forward P/E
Quarterly Revenue Growth (YoY)
Cisco
20
17.6%
Arista
39
37.7%
14
33.7%
Cisco Earns a Buy Rating at These Levels
The 24/7 Wall St. price target of $125.51 carries a buy rating with 90% confidence. The forward valuation supports the rating: about 20 times earnings for a business that expects earnings growth to speed up in FY2027.
The bull case strengthens if hyperscaler orders keep turning into revenue on schedule. The case weakens if gross margin falls below the 65% low end of guidance. On balance, I think the comeback is real.
These longer-range figures extend the model's base case:
Year
Price Target from 24/7 Wall St.
2026 (January 2027 milestone)
$109.93
2027
$125.51
2028
$138.03
2029
$149.74
2030
$162.45
These projections assume Cisco keeps executing on Silicon One and its optics strategy. A slowdown in hyperscaler spending or new tariff pressure could pull results well below this path.
Released: The Definitive Guide to Retirement Income
(Sponsor) Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out.
It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan. That is exactly what The Definitive Guide to Retirement Income helps answer. It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn more here. Learn More Here ›
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
